Huang Yiping │ Controlling the total amount is not as good as controlling the sectors, and controlli

On the morning of March 21, Professor Huang Yiping, Vice Dean of the National School of Development at Peking University and Director of the Peking University Digital Finance Research Center, spoke at the Meng Minwei Concert Hall at Tsinghua University.Attended the inaugural "Tsinghua PBC School of Finance Chief Economist Forum". This forum was hosted by...The event was jointly hosted by the Center for International Finance and Economics Research (CIFER) of the National Institute of Financial Research at Tsinghua University and JD Digits.With the theme of "China and the World Economic Outlook 2019",Several chief economists and leading scholars from renowned domestic and international institutions were invited to discuss the development trends and policy directions of the Chinese and global economies.
Professor Huang Yiping and his team collected37 yearsLeverage ratio data for 43 economiesDiscover:After controlling the leverage ratio, the overall leverage ratio level is not very important; the differences in leverage ratios between different sectors are very significant, and the leverage structure is more important than the total amount; the so-called key "threshold" has no significant impact.
Therefore, Professor Huang proposed two policy recommendations:Controlling the total amount is not as good as controlling the sector; a one-size-fits-all approach to deleveraging is not as good as structural deleveraging; controlling the level is not as good as controlling the growth rate; and stabilizing leverage is more appropriate than deleveraging.

Huang Yiping is the Vice Dean and Professor of the National School of Development at Peking University, and the Director of the Digital Finance Research Center at Peking University. From June 2015 to June 2018, he served as a member of the Monetary Policy Committee of the People's Bank of China. Huang also holds the Rio Tinto Chair Professorship in Chinese Economics at the Crawford School of Public Policy, Australian National University, and is a member of the China Finance 40 Forum and the China Economic 50 Forum. He is the Editor-in-Chief of the English academic journal *China Economic Journal* and the Associate Editor of *Asian Economic Policy Review*. His main research areas are macroeconomics and international finance.
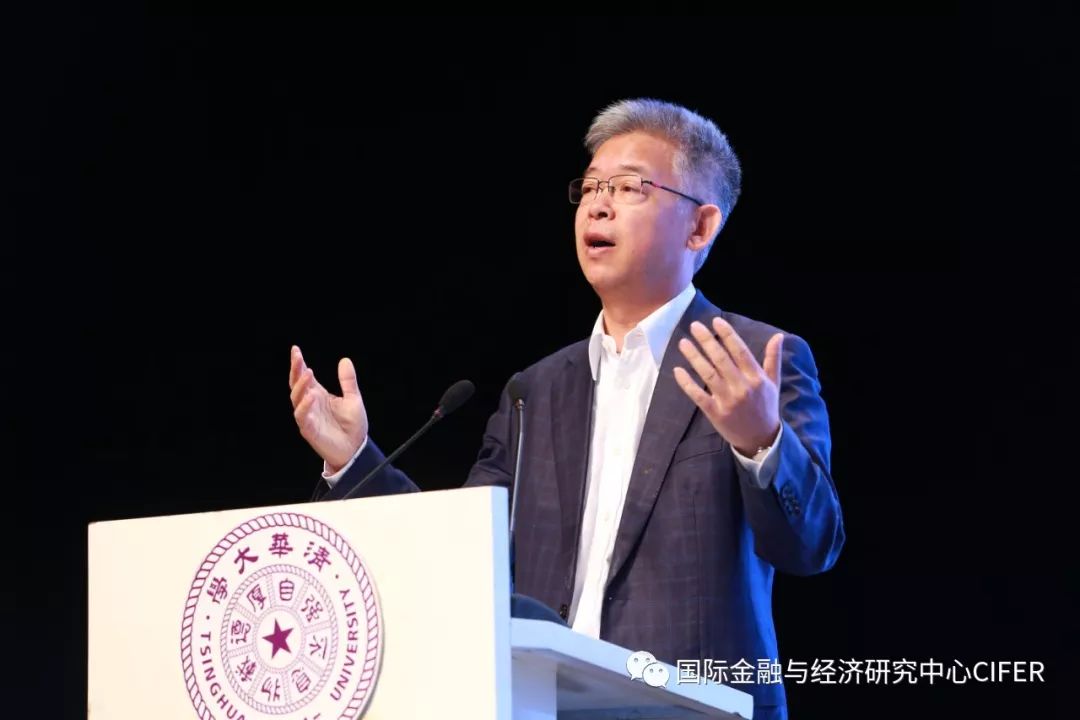
The following is the full text of Professor Huang Yiping's speech:
First of all, I would like to extend my warmest congratulations on the convening of the Tsinghua PBC School of Finance Chief Economist Forum! Today I would like to share a recent study that I conducted with Ji Yang, Ge Tingting, and Bian Wenlong.If leverage leads to financial risk, we want to know what leverage ratios and where leverage ratios pose greater risks.
First, let's look at the evolution of China's leverage ratio over the past few years. First, the overall leverage ratio has grown rapidly, which is the main reason why China's high leverage became a global concern some time ago. A high leverage ratio is noteworthy, but perhaps even more noteworthy is the sharp rise in China's leverage ratio after the global crisis. However, if we look closely, we should notice that the overall leverage ratio seems to have shown signs of stabilization in the last year or two. Second, the government's leverage ratio has also been rising, but compared to both developing and developed countries, it seems to be at a relatively low level. Third, corporate leverage has risen particularly rapidly and is already at a high level globally, far exceeding the average level of developing and developed countries. However, recently, a clear trend of stabilization or even decline has been seen. Finally, the household leverage ratio is not that high, but its recent upward trend is also quite evident.
Since at least 2016, deleveraging has become a major policy focus in my country. In 2018, the deleveraging policy sparked considerable controversy, with some arguing that it exacerbated downward economic pressure. In fact, there is no consensus, either in academia or politics, on what constitutes appropriate deleveraging. This can be reflected in the following three aspects.
First, is the leverage ratio problem due to excessively high levels or excessively rapid growth? In other words, should the focus of economic policy be on deleveraging or stabilizing leverage? Scholars representing both sides have expressed differing opinions, which I won't list due to time constraints. Second, should the government increase or decrease leverage? Scholars also hold opposing views. Finally, should our future leverage ratio adjustments shift from the highly leveraged corporate sector to the relatively less leveraged household sector?
Our research explored two main questions. First, we wanted to examine whether the level of leverage or its growth rate was the primary driver of financial risk. Second, we wanted to see if the impact of leverage levels and growth rates differed across different sectors.
We collected data from 43 economies from 1980 to 2017 for empirical analysis. Let's first look at what this data tells us intuitively. We calculated two sets of data for some leverage ratio indicators. The first set is the sample average for all countries and all years, and the second set is the sample average for countries that experienced financial crises in the five years prior to the crisis. Comparing the two sets of data reveals some interesting phenomena.Looking at the overall leverage ratio and sectoral leverage ratios, the average of the five years before the crisis was lower than the average of the entire sample.This at least raises questions about the assertion that "high leverage ratios can easily trigger financial crises."
However, if we look at the growth rate of leverage, we can see that in the five years before the crisis, total leverage and sectoral leverage were indeed much higher than the average of the entire sample.The only exception was the government leverage ratio, whose growth rate in the five years prior to the crisis was far lower than the average of the entire sample. All other leverage ratio indicators showed a significant acceleration before the crisis. This change was also reflected in the difference in growth rates between the private and government leverage ratios, as well as between the household and corporate leverage ratios. In other words, it was clearly observed before the crisis that the growth rate of the private sector's leverage ratio (households and businesses) was significantly faster than that of the government leverage ratio, and the growth rate of the household leverage ratio was significantly faster than that of the corporate leverage ratio.
We then used this set of data to conduct some regression analysis, the main purpose of which was to explain what kind of leverage ratio directly led to the increase in the risk of financial crisis.
We found that simply including leverage level in the regression equation might make it a significant explanatory variable. However, when we added leverage growth rate, the level variable became insignificant, while the growth rate variable became highly significant. In other words, at least based on international experience, the growth rate is far more important than the level.More importantly, from a structural perspective, the difference in the growth rate of private sector leverage relative to government leverage and the difference in the growth rate of household leverage relative to corporate leverage both have significant explanatory power for the risk of financial crises.
What might be the mechanism behind these results? We conducted some investigations and found that the significant variables mentioned earlier significantly increase the level of real interest rates, reduce fixed capital formation, and decrease TFP growth. If these variables are significant, they do indeed have some real impact on the real sector.
Here's another issue. You may have heard of the discussions by American economists Reinhart and Rogoff regarding the impact of public debt on economic growth. They found that if public debt exceeds 90% of GDP, a country's economic growth declines significantly. Initially, they predicted a recession, but later realized their calculations were incorrect, though they still observed a significant slowdown in growth. If their analysis is accurate, it suggests there might be a significant threshold for leverage, above and below which economic and financial performance differs significantly. We also tried to verify this "threshold" idea. However, no matter how we used different thresholds to measure the sample, we found that the conclusions remained unchanged. Our hypothesis is that the so-called level effect or threshold effect is simply due to the lack of important explanatory variables.
We also conducted some heterogeneity analysis, and the basic conclusion is that economic systems and institutions have a significant impact on the risk of financial crises. For example, a high degree of financial repression exacerbates the financial risk of leverage ratios. High-quality regulation in an economy can mitigate the risk of leverage ratios. Finally, high transparency of credit enhancement information can also mitigate the risk of leverage ratios. In other words, although the growth rate of leverage is dangerous, good policies and institutional environments can reduce the degree of these risks.
In conclusion, we have made three basic findings:
No.oneFirst, if the leverage ratio is controlled, the overall leverage ratio level is not very important. Second, the differences in leverage ratios between different sectors are very significant, meaning that the structure of leverage may be more important than the total amount. Third, the impact of the so-called critical threshold is not significant.
Finally, based on our analysis, I'd like to offer a simple policy recommendation. However, I should clarify that while this study used multinational data, it can still provide some valuable policy suggestions:
First, controlling the total amount is not as effective as controlling specific sectors, which means that a one-size-fits-all approach to deleveraging may not be as effective as structural deleveraging.
Second, controlling the level is not as good as controlling the growth rate, which means that stabilizing leverage may be more appropriate than deleveraging.
Thank you everyone.