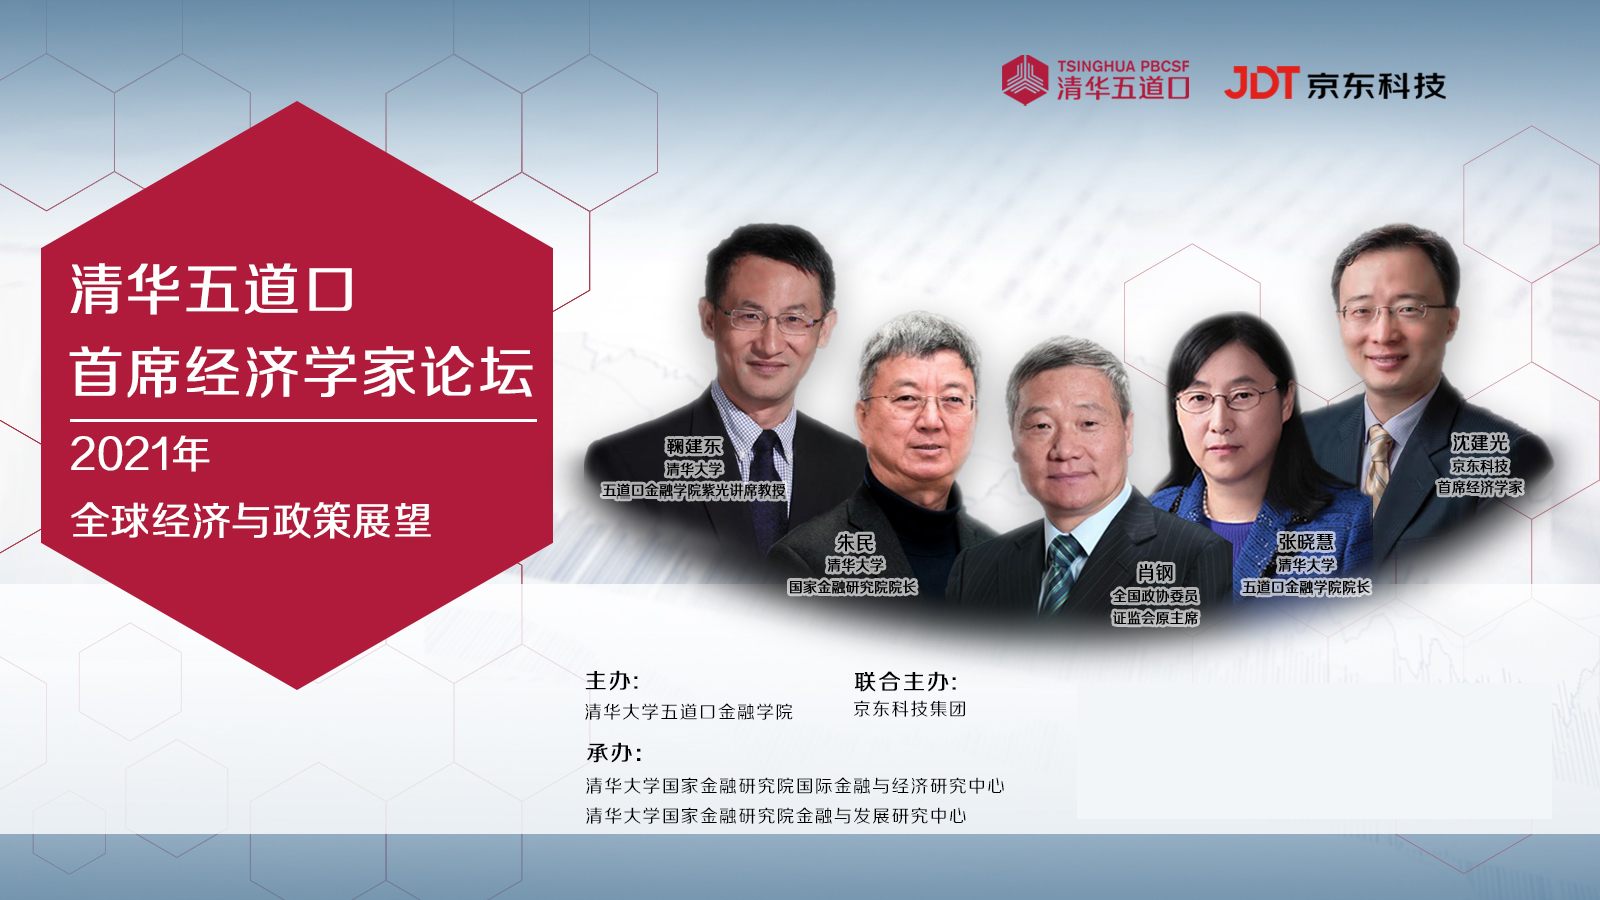
Recently, a conference was held, hosted by Tsinghua University's PBCSF (Public School of Finance), co-hosted by JD.com, and organized by the Center for International Finance and Economics Research (CIFER) and the Center for Financial and Development Research (CFD) of Tsinghua University's National Institute of Financial Research. “Tsinghua University PBC School of Finance Chief Economist Forum – 2021 Global Economic and Policy OutlookThe event was broadcast live on 27 platforms across the internet, attracting attention from nearly 100 media outlets and drawing over 10 million viewers.Professor Ju Jiandong, Ziguang Chair Professor of Tsinghua University's PBC School of Finance and Director of the Center for International Economics and Finance Research (CIFER), served as the forum's chief moderator.
The second roundtable discussion was moderated by Wang Tao, Chief China Economist at UBS Group.The guests attending Roundtable Forum (II) were:The chief economists were Cui Li, chief economist of CCB International; Zhang Zhiwei, chief economist of PICC Investment Management; Guan Tao, global chief economist of BOC Securities; and Wu Ge, chief economist of Changjiang Securities. The chief economists discussed..."China's Macroeconomic and Policy Outlook"This topic was discussed in depth, with many arguing that China will be the first to normalize its policies in the post-pandemic global policy landscape and economic recovery process. Within the basic framework of cross-cycle adjustment, China has established a tone of continuity, stability, and sustainability for its macroeconomic policies. Economists hold differing views on China's economic growth, inflation, and policy trends.
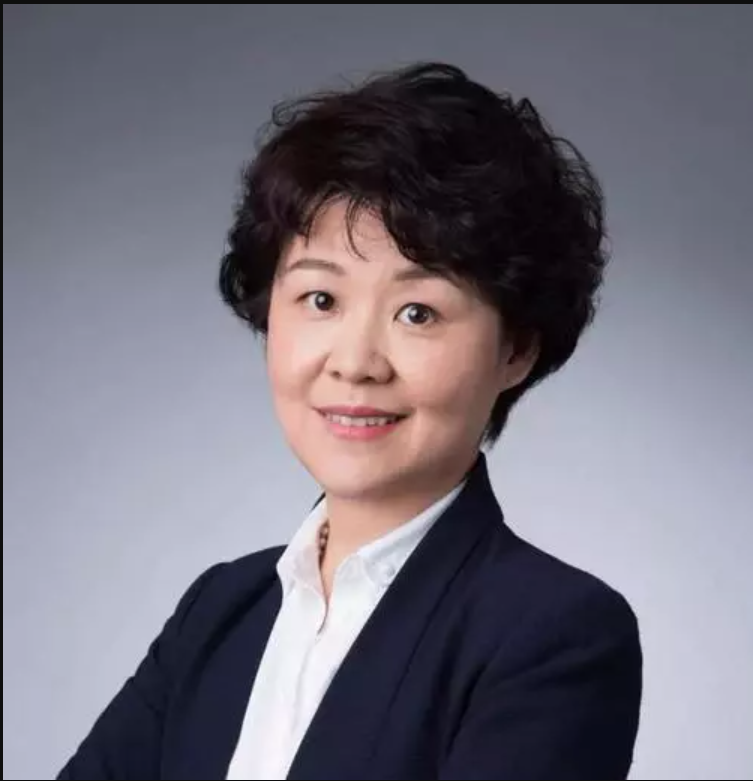
Cui Li CCB International Chief Economist Cui Li attended the second roundtable forum on "China's Macroeconomic and Policy Outlook" and stated in his speech that...The high-tech industry has been the main driver of this year's economic recovery. The pandemic has accelerated the transformation and upgrading of China's industries, and the potential growth rate may have bottomed out and rebounded. A gradual tightening of macroeconomic policies is highly probable, and reflation will likely lead to further increases in long-term interest rates, while policy rates are likely to remain unchanged. Industrial policies will be a more important focus in the coming years.
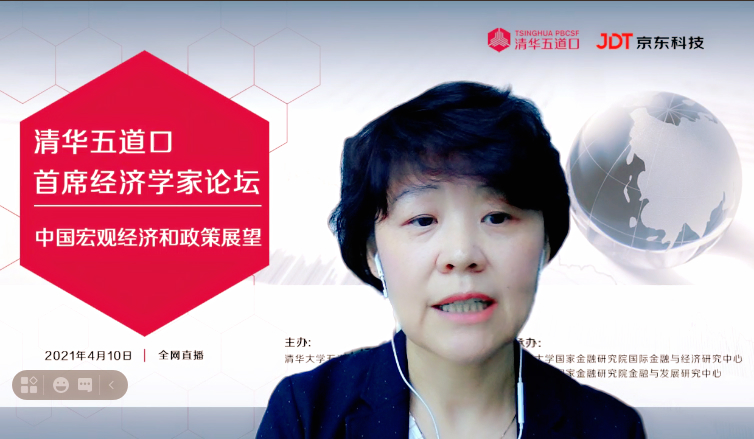 Cui Li's speech
The following is the full text of the speech (not reviewed by the guest):
Cui Li: Thank you, Chief Scientist Wang Tao, for the introduction. I am very pleased to have the opportunity to participate in this forum, and thank you to Tsinghua University's PBC School of Finance for the invitation. I have been very inspired by the speeches of Chairman Xiao, Dean Zhu, and Dean Zhang, as well as the speeches of the previous speakers.Wang Tao just mentioned some macroeconomic forecasts for the Chinese economy, and my views are similar. Looking at the major indicators, our forecast for industrial producer prices is slightly higher because global inflation expectations are relatively strong this year, which may drive up industrial product prices more significantly. However, the impact on downstream consumer goods prices may not be as strong, so the CPI is expected to remain relatively stable.Today, I'll mainly be discussing some medium-term perspectives. Aside from the short-term outlook, specifically this year's, I'll look at the structural changes in China's economy over the next few years. I strongly agree with Chairman Xiao and Dean Zhu's points that economic transformation, including differentiation, is a very important and noteworthy trend. If we look at China's economic recovery since last year's pandemic, it's different from previous economic recovery efforts. This time, the recovery has been stronger in high-tech and manufacturing sectors. High-tech and advanced manufacturing, along with some consumer spending and online internet industries, have also performed strongly. This is different from the recovery previously driven by the construction industry.In terms of profit margins, we can see a divergence between these two types of industries. The profit margins of construction-related industries are relatively weak, while those of new economy industries are relatively strong, continuing the structural changes of economic transformation that preceded the pandemic. The structural transformation of recent years, and the supply-side reforms since 2016, have revealed several structural changes:1. The proportion of the so-called "old economy"—specifically, the proportion of the real estate and construction-related sectors—is declining, while the proportion of the consumer, healthcare, and electronics industries is rising.2. The so-called old economy and traditional industries are also undergoing consolidation and upgrading. Not only has concentration increased to some extent, but profitability has also improved, and asset efficiency has begun to rise in recent years. In other words, both profitability and ROA have seen sustained progress. These transformations have been further accelerated by the pandemic, including new consumer demands, online consumption, healthcare needs, and the digitalization of the electronics industry. We believe this transformation will continue. Therefore, from a certain perspective, the pandemic has accelerated the transformation and upgrading of China's economic industries.These changes are crucial. They have several impacts:1. From a macroeconomic perspective, the past decade has been a period of decline, a significant reason being the decrease in capital efficiency. Looking at economic growth, the growth rate of total factor productivity is declining. Transformation itself implies more efficient resource allocation, making a future economic recovery from an "L-shaped" trajectory more likely.2. From a market perspective, the logical relationship between the economy and the market may be changing. In the past, during economic downturns, the financial cycle was frequently considered, with the belief that only credit easing could influence corporate profit cycles. This was because overall real growth was declining, and only the financial cycle affected the price cycle, which in turn affected GDP and ultimately corporate profit cycles. However, with future economic transformation and increased corporate growth momentum, the financial cycle is no longer the most critical factor influencing profit cycles. This was evident last year. While there was some easing during the pandemic, the extent was relatively small, primarily addressing cash flow shortages and resulting in only a small increase in incremental growth, although corporate profits saw a significant improvement. We can see a decoupling between the financial cycle and corporate profit cycles. In other words, the future may not follow the old logic. Although policies may tighten somewhat, the changing dynamics of the economy suggest that the upward cycle could be more sustainable. This will benefit not only growth-oriented companies but also traditional ones. This represents a continuous shift in the relationship between the economy and the market.3. From an efficiency perspective, due to improved efficiency, China's risk-free interest rate will not experience a downward trend. Of course, some contraction in savings also supports the risk-free interest rate. However, overall, the trend of China's risk-free interest rate differs from that of overseas rates. Because of our improved efficiency, there is strong support for maintaining a relatively stable risk-free interest rate within a range over the next few years.This development is crucial for our policy judgment. This year, with the economic improvement, policies have begun to gradually tighten. If the industrial cycle becomes a significant driver of the economy, growth itself will no longer require substantial stimulus; macroeconomic policies should focus more on management and policy adjustments. Another issue is risk prevention. Therefore, our policy judgment is as follows:First, as monetary policy gradually withdraws and interest rates are still in the process of recovery, we believe they will rise further, especially long-term interest rates. Because excessively low interest rates and overly loose liquidity can also lead to asset bubbles.In addition, the overall trend of fiscal policy is currently relatively loose. Firstly, the economy has not fully recovered, and some industries still require targeted support; secondly, the scale of special-purpose bonds this year is also quite large, mainly to address the issue of hidden debt.Overall, fiscal policy is relatively loose at this stage, which is still a suitable approach, but there is a certain degree of withdrawal compared to last year.With industrial upgrading, I believe that macro policies will gradually tighten in the next few years. Of course, the pace may be fast or slow, but gradual tightening is still a high probability event, and industrial policies may be an important aspect that policies will pay more attention to.That's all for now. Thank you!
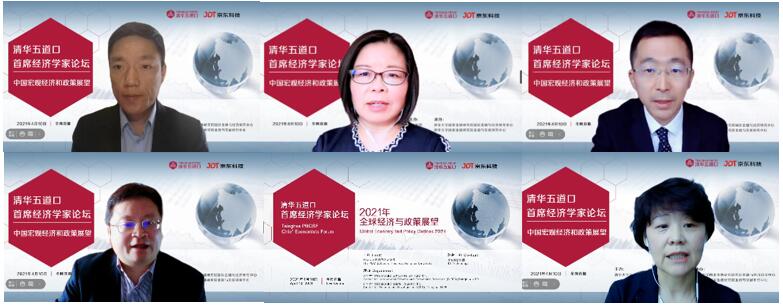 Roundtable (II): Outlook on China's Macroeconomic Situation and Policies - Group Photo of Participants
On April 10, 2021, the "Tsinghua University PBC School of Finance Chief Economist Forum" returned online after a two-year hiatus.This forum consisted of two parts: keynote speeches and roundtable discussions. It was held online and streamed live across the entire network, ensuring a smooth exchange of ideas and perspectives. The forum invited over twenty prominent guests to gather virtually and engage in in-depth discussions on topics such as the global economic outlook, China's macroeconomic and policy outlook, money and credit in the post-pandemic era, and carbon neutrality and the macroeconomy.
 Cui Li's speech
 Roundtable (II): Outlook on China's Macroeconomic Situation and Policies - Group Photo of Participants