Wang Tao | This year, China's economy is expected to achieve a growth rate of 9% driven by domestic
 Recently, a conference was held, hosted by Tsinghua University's PBCSF (Public School of Finance), co-hosted by JD.com, and organized by the Center for International Finance and Economics Research (CIFER) and the Center for Financial and Development Research (CFD) of Tsinghua University's National Institute of Financial Research. “Tsinghua University PBC School of Finance Chief Economist Forum – 2021 Global Economic and Policy OutlookThe event was broadcast live on 27 platforms across the internet, attracting attention from nearly 100 media outlets and drawing over 10 million viewers.Professor Ju Jiandong, Ziguang Chair Professor of Tsinghua University's PBC School of Finance and Director of the Center for International Economics and Finance Research (CIFER), served as the forum's chief moderator.

The second roundtable discussion was moderated by Wang Tao, Chief China Economist at UBS Group.The guests attending Roundtable Forum (II) were:The chief economists were Cui Li, chief economist of CCB International; Zhang Zhiwei, chief economist of PICC Investment Management; Guan Tao, global chief economist of BOC Securities; and Wu Ge, chief economist of Changjiang Securities. The chief economists discussed..."China's Macroeconomic and Policy Outlook"This topic was discussed in depth, with many arguing that China will be the first to normalize its policies in the post-pandemic global policy landscape and economic recovery process. Within the basic framework of cross-cycle adjustment, China has established a tone of continuity, stability, and sustainability for its macroeconomic policies. Economists hold differing views on China's economic growth, inflation, and policy trends.

Wang Tao
UBS Group Chief China EconomistWang Tao predicts that China's economy is likely to achieve a 9% growth rate this year, driven by domestic consumption and exports. Manufacturing investment will also rebound significantly due to substantial increases in corporate revenue and orders. Overall, inflation in China is expected to be under control this year, with monetary and fiscal policies gradually normalizing. A slight interest rate hike is anticipated in the third quarter, with tightening primarily focused on credit policy. Total social financing is projected to grow by 11% for the year. Given that nominal GDP growth this year may approach 12%, the overall macro leverage ratio could decrease by 4-5 percentage points.
 In his speech, Wang Tao
The following is the full text of the speech (not reviewed by the guest):
Wang Tao: I am very grateful for the invitation from Tsinghua PBC School of Finance. It is an honor to have the opportunity to participate in today's PBC School of Finance Chief Economist Forum.Good morning, everyone! Dean Zhang, Dean Zhu, Chairman Xiao!
I am Wang Tao, Chief Financial Officer for China at UBS. As Professor Ju just introduced, the four of us participating in today's discussion will focus on the outlook for China's macroeconomy and policies. We will discuss in more detail this year's economic recovery, structural adjustments, China's inflation problem, and its impact on monetary policy, as well as international policy coordination. Previous forums have covered a lot about the international economic recovery, the Federal Reserve's policies, and so on. Furthermore, we will discuss the impact of the Federal Reserve's policies and the international economic recovery on us and on the market. We also have Zhang Zhiwei, Chief Financial Officer specializing in domestic asset allocation and management, with us today.
As the host, I'd like to start by briefly introducing UBS's views on the Chinese economy and...policyNow, I would like to invite the guests to share their views.
Our overall assessment of China's economy this year is that it will rebound strongly, and policies will be gradually adjusted.
First, we predict that China's economy is likely to achieve a growth rate of 9% this year, driven by domestic consumption and exports. Exports will primarily benefit from the global progress of vaccines, economic normalization, and the large-scale fiscal stimulus implemented by the United States. We believe that full-year export growth will be around 16%, with even the risk of further increases, making it stronger than last year.As the domestic economy further recovers, the labor market, employment, and wages are showing restorative growth, and consumer confidence will also recover further. In particular, services, which were relatively weak last year, may see some restorative growth this year, which will be slightly faster than the growth in product consumption.
Regarding investment, our assessment is that real estate and infrastructure investment may slow down due to marginal tightening of policies, possibly to a low single digit. Meanwhile, manufacturing investment, which has seen a significant decline compared to last year due to substantial increases in corporate revenue, profits, and orders, coupled with uncertainties surrounding trade frictions and the pandemic, is expected to rebound sharply this year, potentially growing by around 10% or more. This rebound in manufacturing investment may offset the slowdown in real estate and infrastructure investment.
One major uncertainty for growth this year, which everyone agrees on, stems from the global pandemic and the development of vaccine supply. Another uncertainty is the real estate market. While policies are tightening, the experience of the past two years has shown that the real estate market has been stronger than expected. Whether this will continue this year is also an uncertainty.In addition, the speed and intensity of policy tightening are of great concern to the market regarding their potential impact on the economy.
I'll focus on two key issues. First, the strong economic growth in China and globally has led to a surge in commodity prices. Will this result in domestic inflation? This is a major concern, and later speakers will provide a more detailed analysis. I'll share our forecast. The Producer Price Index (PPI) is expected to rise by an average of over 3% this year, with upstream prices seeing the largest increases. However, the price increases for core manufactured goods and consumer products downstream are likely to be limited, given the intense competition in the downstream market. The Consumer Price Index (CPI) is expected to be lower in the first half of the year and higher in the second half, mainly due to base effects. Pork prices have entered a downward cycle and are unlikely to reverse anytime soon. Influenced by this, we believe the average CPI for the year will be above 2%, with the second half potentially reaching 2.5% or higher.
Second, considerations and speed of policy exit. We just discussed that inflationary pressures are controllable. Why did China take the lead in proposing policy normalization and exiting stimulus policies? We mentioned earlier that the US and the Federal Reserve consider this from the perspective of inflation expectations. In China, the main consideration is controlling risk and stabilizing leverage, which is a very important consideration because inflation is controllable and not currently the primary concern. Considerations for policy and the sustainability of economic growth are particularly important. In the short term, there was a strong impact from the pandemic, and effective policies were introduced. After economic recovery, policies will be adjusted relatively quickly. Regarding the exit of monetary policy, we believe that the central bank will tighten marginal liquidity, but more importantly, it will reduce the growth rate of credit, mainly through macro-prudential tools. Last year, there were many regulatory understandings encouraging banks to lend to struggling businesses. This year, there will be a greater emphasis on strict risk management, thus changing the intensity of regulation. There are also the three red lines, the upper limit on real estate credit, etc., which I categorize under macro-prudential regulation. This includes tightening regulations on shadow banking and internet finance. This year, social financing will grow by about 15%, compared to about 13.8% last year, but the tightening will not significantly lower economic growth. Unlike last year, there aren't as many companies borrowing money to survive.
Simply put, nominal GDP growth this year may only be 12%, compared to around 3% last year. The central government's goal of controlling and stabilizing leverage this year is achievable. We estimate that the macro leverage ratio may decrease by 4-5 percentage points this year, compared to an increase of 24 percentage points last year; this is our basic assessment.
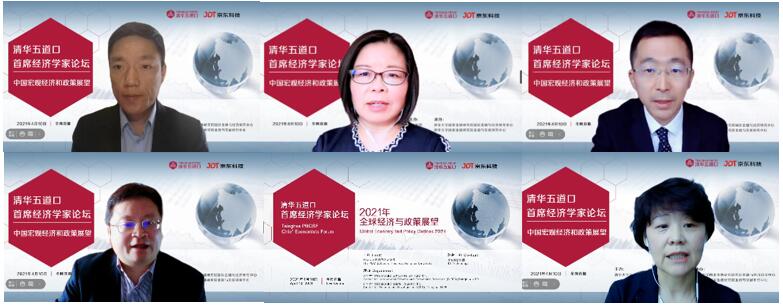
Roundtable (II): Outlook on China's Macroeconomic Situation and Policies - Group Photo of Participants
On April 10, 2021, the "Tsinghua University PBC School of Finance Chief Economist Forum" returned online after a two-year hiatus.This forum consisted of two parts: keynote speeches and roundtable discussions. It was held online and streamed live across the entire network, ensuring a smooth exchange of ideas and perspectives. The forum invited over twenty prominent guests to gather virtually and engage in in-depth discussions on topics such as the global economic outlook, China's macroeconomic and policy outlook, money and credit in the post-pandemic era, and carbon neutrality and the macroeconomy.